Bedford pilot · free business account
Do good locally.
Be known for it.
Give what your business is good at: something from a school's wishlist, your spare stock, a free service, or your team's time and skills. Local schools and charities confirm every gift, so you can tell your story and use it in tenders.
No monthly fee in the pilot. Give goods, a service or your time.
Four ways to give
Give what suits your business.
New goods
Buy exactly what a school or charity has put on its wishlist.
Surplus goods
Give spare stock, furniture or equipment you no longer need.
Donated services
Do a job for free, from a minibus safety check to PAT testing.
Skills and volunteering
Careers talks, mentoring and team days. Larger employers can bring their whole team with one company account.
Local wishlists
Small things that make a big difference.
 Sport
 Rivertree Free School
Footballs and bag for playground
To help children stay active and entertained out on the playground.
1 still needed
 Art & craftLivingstone Primary School
a3 good quality white sketching paper
Our art department requires extra resources for the Autumn term. Minimum 60 sheets required.
2 still needed
 Other
 Fun 4 Young People (F4YP) Ltd
Sensory Room light
1 still needed
OtherHopeWorks UK (Bedford)Upriver Emergency Sleeping Bag
These are items that are regularly used by those who are facing homelessness.
1 still needed
Swipe to see more
Wishes from public school and charity profiles. Browse local wishlists to choose your area.
Browse local wishlistsHow it works
From one gift to a lasting local connection.
- 1
Choose what to give
A wish, something spare, a job or your team's time, near your office or your patch.
- 2
Give it
Buy and send it, drop it off, do the job or turn up and help.
- 3
They confirm it
They confirm delivery. A thank-you or public story is optional and follows their permission. Keep talking about the next need, a visit or work experience.
What your business gets back
Good deeds are worth talking about.
For CSR reports and tenders
Every gift and every hour, on the record.
Schools and charities confirm receipt or that an activity happened. Your dashboard brings those confirmations together with business-declared values and recipient figures for your CSR report or bid.
Your social value dashboard
What you gave, where it went and how local it was, with reported or estimated beneficiary engagements and the ranking of recipient neighbourhood locations in England.
A Tender Pack in one click
A printable pack explaining your records and how each figure is made. Buyers decide which evidence is relevant and how it is scored.
Every record as a CSV
For your bid team, your accountant or your social value platform.
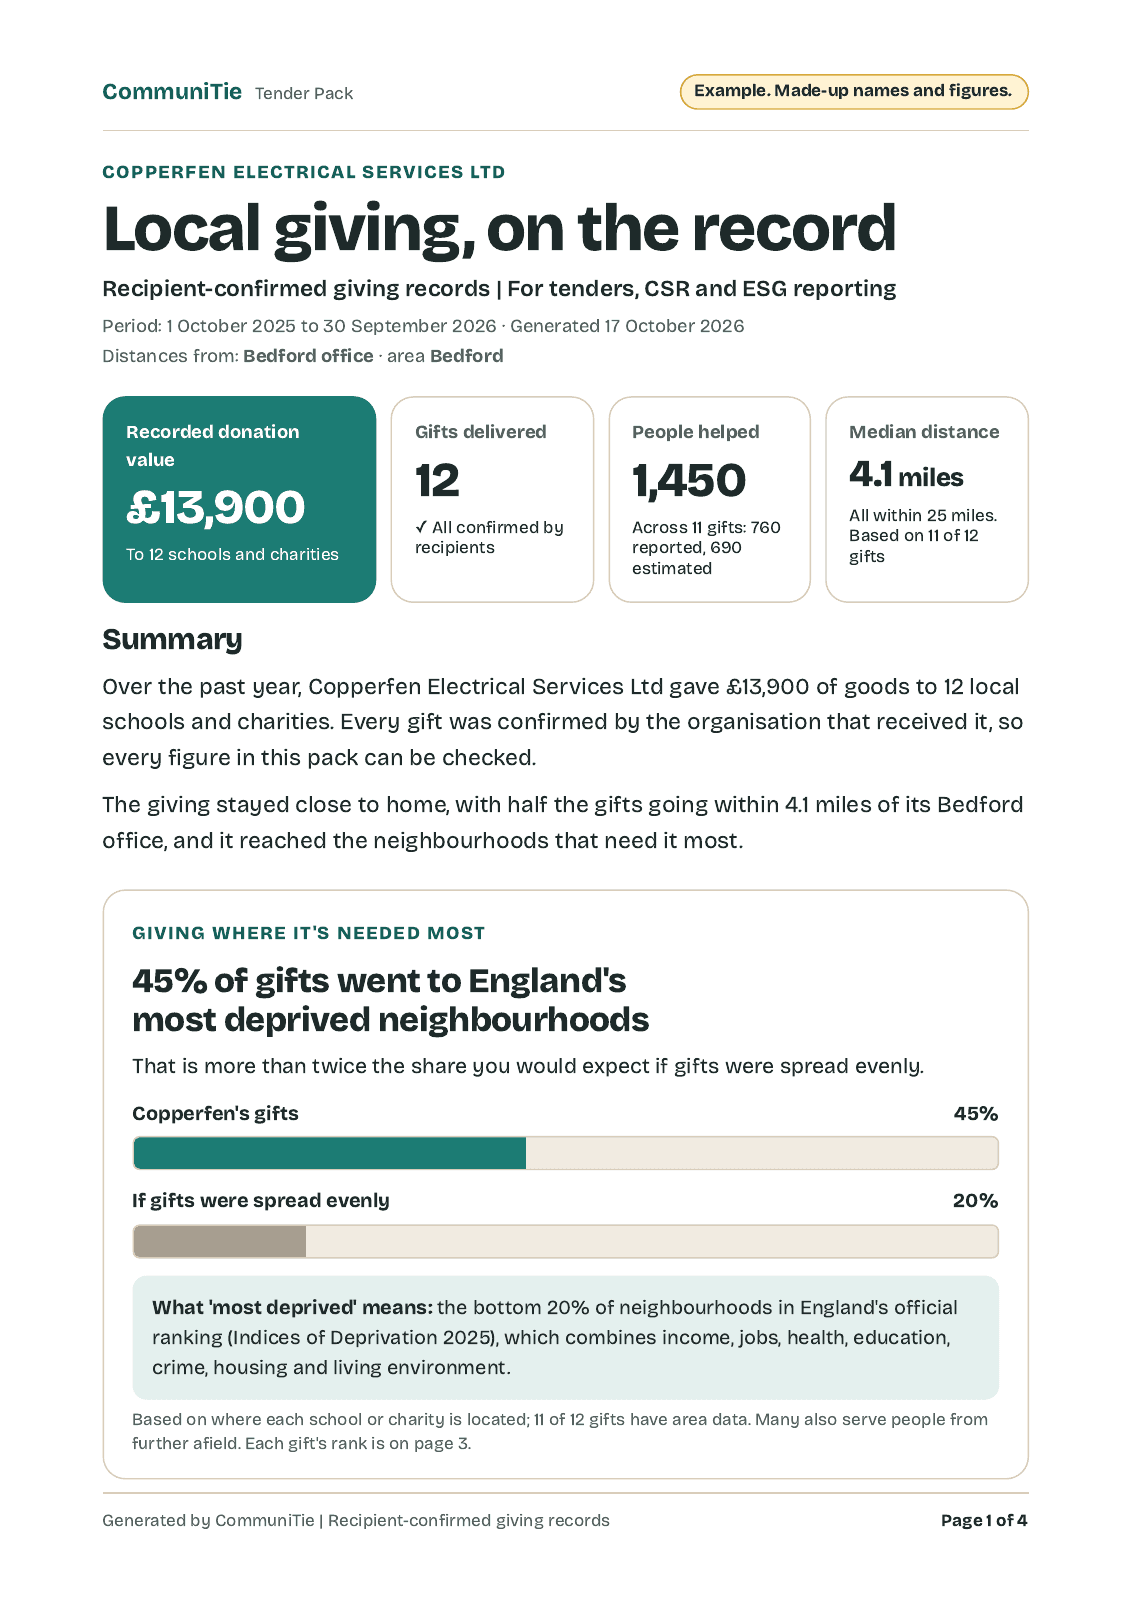
Recipient confirmations record what happened. Values are business-declared; beneficiary engagements are recipient-reported or estimated, not independently verified outcomes.
Tax example: buying goods to donate
An illustrative laptop purchase, separate from donating stock or equipment you already own
A £200 item can cost your business about £125
For a VAT-registered company paying 25% corporation tax.
Illustration only, not a guaranteed saving. Assumes a VAT-registered company can recover all £33.33 purchase VAT, deduct the £166.67 cost against profits taxed at 25%, and make a qualifying donation without a VAT charge. You pay the supplier £200 upfront; any tax relief follows later. Ask your accountant whether these assumptions apply.
See the maths
An illustrative laptop purchase, separate from donating stock or equipment you already own
For a £120 purchase: You pay the supplier £120 upfront. Only if full purchase VAT recovery and a 25% corporation tax deduction apply, and the donation qualifies, the illustrative after-tax cost is £75. This is not a guaranteed saving or a social value score.
Check the donation, not just the school type
HMRC VAT Notice 701/1, sections 2.1 and 5.5, sets the conditions. A school name, URN or category alone does not establish eligibility. Check the receiving legal entity, its charitable status and HMRC recognition, eligible use and written evidence.
The donation must be freely given without anything in return, for onward donation or the charity’s non-business activities. Services do not qualify for this goods relief.
The limit is £100 excluding VAT per item, or £200 for household appliances, furniture including mattresses, flooring, computers including tablets, and mobile phones. Use the lower of original purchase or production cost and the cost of an identical item at donation, allowing for age and condition, excluding VAT. Monitors and other accessories are not automatically in the higher tier. Alcohol, tobacco and duty-liable vaping products are excluded. Over-limit items do not qualify for this relief.
Input VAT recovery follows normal business rules. The 2026 relief concerns VAT on the gift itself; it does not create a right to reclaim purchase VAT. Corporation tax deductions depend on the expense, trading stock or asset rules, available profits and the company’s tax position. Donating existing stock does not create a second purchase deduction.
These tax illustrations do not measure social outcomes or predict tender scores. Obtain professional tax advice before relying on them.
Our partners
We also work closely with Bedford Borough Council and Bedford Borough Learning Exchange.
Before your first gift
Good questions.
What does it cost?
Nothing to join during the Bedford pilot. If you buy a wish, you pay for the item and any delivery. Schools and charities use CommuniTie free.
Do I need a big budget or a CSR team?
No. Start with a small, useful gift, something spare, or an hour of your team's time.
Can we give time instead of money?
Yes. Offer careers talks, mentoring, practical help or team days. Schools and charities confirm the hours, and time is never turned into a money value.
Will the school definitely thank me publicly?
Thank-yous are strongly encouraged and made quick for schools, but they’re never compulsory, and public sharing follows the school’s permission.
Can I claim VAT relief?
It may apply to eligible goods, recipients and uses within HMRC’s per-item limits. Purchase VAT recovery and corporation tax follow separate rules. Your accountant should check your circumstances; relief is not guaranteed.
Can I use this in a tender?
You can use the records as supporting evidence. Recipient confirmation records receipt or that an activity happened; it does not independently verify business-declared values, outcomes or procurement relevance. People-helped figures are recipient-reported or estimated engagements, not unique people. The buyer decides eligibility and scoring.
More answers in the FAQ.
Your next good deed is probably on your street.
Free for schools and charities